
Hello Avatar! Welcome to another week of biotech analysis. Today’s commentary, as always on Thursday, focuses on the general market update. This week confirmed the playbook. Biotech can rally and capital can return quickly, but funding is flowing to companies with clean catalysts and tight execution. Secondaries continue to dominate the financing landscape, while IPO activity remains scarce. Investors are rewarding near-term proof and punishing duration risk. In this environment, cost of capital shapes trial design, and clock discipline matters as much as mechanism.
We are now publishing 7x per week according to the following cadence:
Mondays: Stocks
Tuesdays: Biotech
Wednesdays: Podcast
Thursdays: Markets
Fridays: News
Saturdays: Podcast
Sundays: Strategy
We are also publishing unique content on X - be sure to follow up if you are not already @BowTiedBiotech. And to check-out the archive of our work on X you can find it on our website at: BowtiedBiotech.subtack.com/x-articles.
SUBSCRIBE TO PODCAST HERE:
Please help spread the work by subscribing and hitting the share button if you are enjoying content!
Lots to cover this week, let's get started!
BIOTECH PUBLIC MARKET UPDATE
For the week, the public indexes were MIXED, with the S&P -1.6% and DOW moving +0.5%. For the year the public indexes are UP, with the S&P up +16.7% and DOW up +17.3%. The XBI (the biotech index) comes in UP approximately +8.5% for the week and is up approximately +24.1% for the year.

Macro Update
Most investors view the AI buildout as a technology story. Nvidia benefits. Hyperscalers spend. Software companies promise productivity gains. Biotech appears several steps removed from the discussion.
Look closer. AI is becoming an infrastructure story. The bottleneck is no longer only chips or models. It is power. A new ICF report says the U.S. grid may need 445 GW of added capacity by 2030, with peak-adjusted growth close to the size of PJM, the largest regional grid in the country. The same report notes that the U.S. has only 26 GW of excess generating capacity today, roughly 3% of total capacity, with no surplus expected in fast-growing regions like Texas and PJM beyond 2027. Grid upgrades could exceed $1 trillion over the next decade.
That matters because investors spent the last two years pricing AI like software. Software scales cleanly. Infrastructure does not. Data centers need electricity, water, land, transformers, cooling, interconnection agreements, and local political tolerance. The market can model GPU demand in a spreadsheet. It has a harder time modeling a substation delay, a permitting fight, or a power constraint that pushes a data center project back by years.
Biotech has the same problem in a different costume. The industry loves scalable stories. AI drug discovery. Platform biology. Automated labs. Modular cell therapy manufacturing. But translation always runs into physical constraints. Patients must enroll. Sites must execute. Assays must work. CMC must scale. Regulators must trust the package. A discovery engine that generates more targets does not solve the bottleneck if the company cannot convert those targets into clean human data.
This dynamic does not impact every biotech equally. Companies with real clinical infrastructure, strong manufacturing control, and validated development playbooks deserve more credit. Early-stage platform stories face a higher bar. Investors should ask whether a company’s technology actually removes a bottleneck or only creates more shots that still need the same expensive clinical funnel. Faster discovery helps. Faster translation matters more.
The market still treats the AI power squeeze as a tech and energy story. That is likely too narrow. For biotech, the lesson is that every boom eventually meets its constraint. AI met the grid. Biotech meets translation. The companies that win will not necessarily have the flashiest platform. They will be the ones that control the limiting step between a good idea and a real product.
Introduction
This week, the more interesting biotech story is not another single-asset catalyst. It is the quiet rebuild of the industry’s translation layer. China has moved from “cheap follow-on science” to something more threatening. It now turns mechanisms into human data fast enough for Big Pharma to treat the country as external R&D inventory. That changes how you should think about U.S. platform premiums, BD scarcity, and the value of early clinical proof. The market still wants to debate whether China is innovative. That is the wrong fight. The better question is which therapeutic ideas now get tested, killed, licensed, or globalized before Western biotechs can finish telling you why their platform is special.
Why this matters now
China biotech used to be an easy paragraph. Cheap CROs. Me-too PD-1s. Local oncology trials. A few assets licensed out when Western pharma wanted optionality without paying U.S. venture prices. That version is dead. You can still hear it on panels because people like old heuristics. The data moved on.
The current setup is more uncomfortable. China now sits within striking distance of the U.S. in early-stage drug development share. Georgetown researchers found that U.S. share fell from about 48% in 2015 to just over 37% in 2024, while China rose from 8% to just over 32%. That is not a small base effect anymore. That is a rebuilt machine. The total early-stage pipeline also expanded 82.4% over the same period, which means China did not just steal share in a flat market. It helped expand the market.
The weird part is that investors still frame this as a licensing trend. That misses the better read-through. Licensing is the visible output. The real product is a translation system that turns target ideas into human data faster, cheaper, and often with enough quality to force Big Pharma to care. China did not simply become a source of molecules. It became a place where therapeutic hypotheses get stress-tested at scale before U.S. biotech can finish explaining why its platform deserves another crossover round.
The easy take is wrong
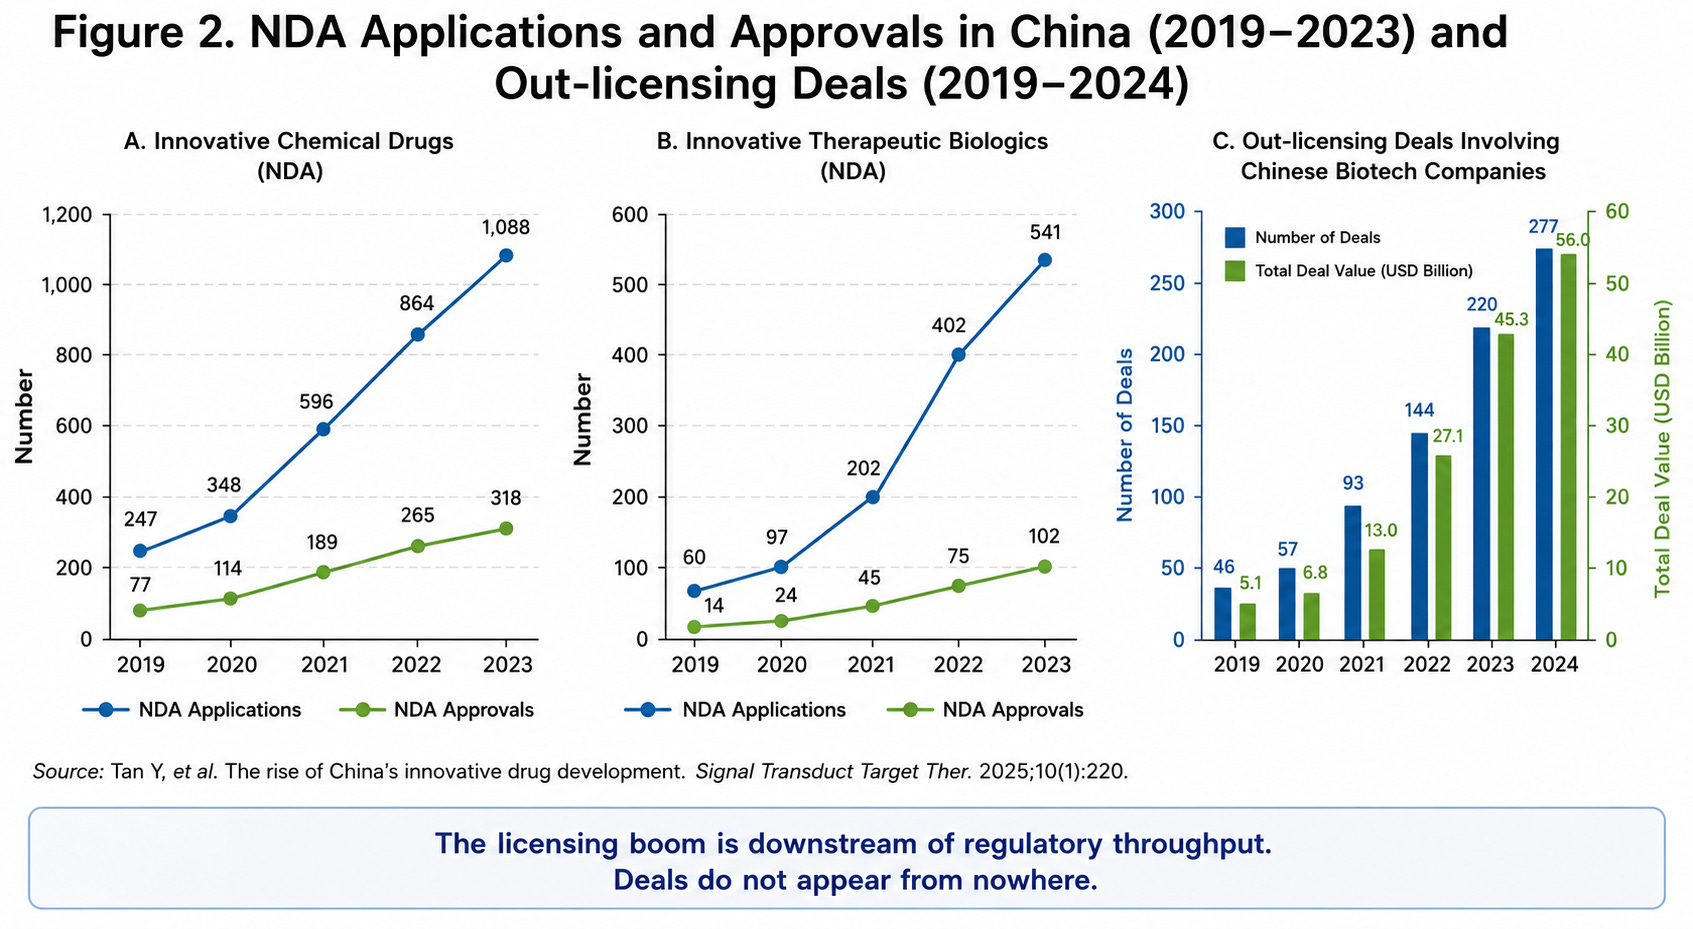
The lazy take says China is winning because labor is cheap and the government subsidizes everything. Fine. Costs matter. Policy matters. But that explanation is too neat. Cheap input costs alone do not create a Pfizer 3SBio deal with a $1.25 billion upfront payment and up to $4.8 billion in milestones for SSGJ-707. They do not explain BMS paying Hengrui $600 million upfront in a broader deal that can reach about $15.2 billion across oncology, hematology, and immunology programs.
The better explanation is that China compressed the distance between “interesting mechanism” and “clinically negotiable asset.” That word matters. Negotiable. Big Pharma does not need every Chinese asset to be de-risked. It needs enough human signal, enough manufacturability, enough biology, and enough competitive urgency to justify buying before someone else does. China now produces that package with frightening efficiency.
This is why investors should stop asking whether Chinese biotech is first-in-class or me-too. The cleaner question is whether China has become the fastest global market for turning a mechanistic thesis into a licensable translation package. In oncology, multispecifics, ADCs, and immunology, the answer increasingly looks like yes. That does not make every asset good. It makes the funnel dangerous.
The translation edge is operational, not mystical
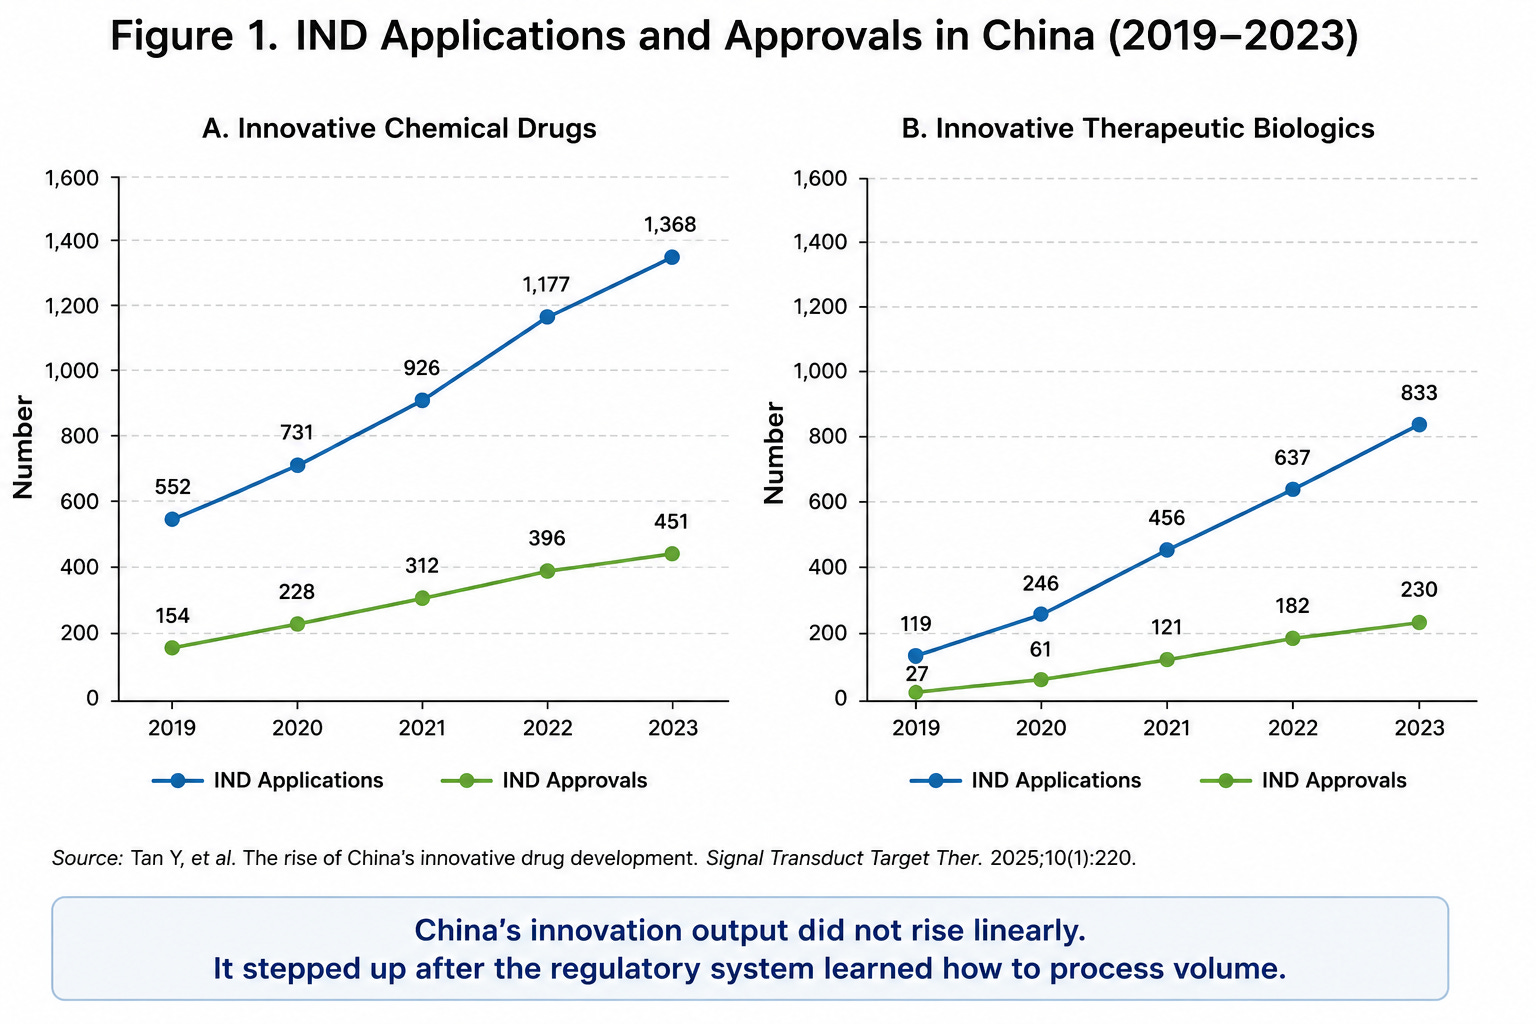
China’s NMPA reforms matter because speed compounds. The 2025 review by Tan and colleagues describes China’s shift from a generics-heavy system toward an innovative drug ecosystem built around regulatory modernization, clinical trial expansion, manufacturing capability, and global collaboration. The same paper shows innovative chemical drug IND applications rose from 552 in 2019 to 1,368 in 2023. Innovative therapeutic biologic IND applications rose from 119 to 833 over the same period. That is a huge change in throughput.
Throughput changes behavior. When a company can move more shots into humans, it becomes less precious about each individual mechanism. That sounds bad to a U.S. investor trained to worship capital discipline. But in therapeutic translation, excessive preciousness is its own disease. You get elegant platform slides, underpowered mouse models, and five years of “we are still optimizing.” China’s model makes a different trade. Push more into human testing. Kill faster. License what survives.
This is not automatically superior. It can create low-quality redundancy, weak trial design, and noisy assets that look better in China than they will under FDA scrutiny. But the market does not need the whole machine to be clean. It only needs a repeatable minority of assets to clear Western diligence. That is the uncomfortable part. A messy factory can still produce enough winners to reset pricing for everyone else.
Big Pharma already voted
Pfizer’s behavior tells you more than the conference panels. It licensed 3SBio’s PD-1 and VEGF bispecific SSGJ-707 for $1.25 billion upfront, plus a $100 million equity investment, with potential milestones up to $4.8 billion. Pfizer also retained an option for China commercialization rights. This is not a tiny ex-China bet. This is a major pharma paying real money to enter a competitive class led by Chinese-origin biology.
BMS went broader. The Hengrui deal covers 13 early-stage programs, including Hengrui oncology and hematology assets, BMS immunology assets for China, and joint discovery programs. Hengrui gets up to $950 million in upfront and near-term payments, with total potential deal value around $15.2 billion. Reuters framed the agreement as part of Hengrui’s push to diversify away from generic pricing pressure under China’s centralized procurement system. That matters. China’s domestic pricing pressure is forcing its best companies to export innovation, not just products.
That is the read-through people underweight. U.S. pharma wants pipeline. China pharma needs global monetization. Both sides have structural pressure to transact. That creates a bid for translation-ready assets, and it starves U.S. small-cap biotech of scarcity value. If you own a U.S. company with a Phase 1 bispecific, ADC, or immunology program, you are no longer competing only against other U.S. small caps. You are competing against the global clearance rack, except the rack now includes real drugs.
Ivonescimab is the case study investors keep misreading
Ivonescimab is the cleanest symbol of this whole shift because it irritates both bulls and bears. Bulls want it to prove that Chinese-origin immuno-oncology can beat Keytruda. Bears want it to collapse under global confirmatory data. The truth is more annoying. It has already done enough to change business development behavior, while still leaving real questions about OS, regional generalizability, and FDA appetite.
Akeso’s HARMONi-2 showed ivonescimab monotherapy improved progression-free survival versus pembrolizumab in first-line PD-L1 positive NSCLC, and the drug gained approval in China. Summit has emphasized that ivonescimab remains investigational in its licensed territories, including the U.S. and Europe. More recent HARMONi-6 data in China showed an overall survival benefit for ivonescimab plus chemotherapy versus tislelizumab plus chemotherapy in first-line squamous NSCLC.
The bear case still has teeth. Progression-free survival can flatter IO plus anti-angiogenic biology. OS is harder. Control arms matter. China-only trials do not automatically translate to U.S. label value. Fierce noted that earlier OS data from HARMONi-2 failed to impress some observers, partly because the analysis was interim and the statistical bar was high. That is the point. China can create the signal. Western development still decides whether the signal becomes a drug franchise.
The overlooked theme is not China versus U.S. science
Reuters reported that the Cure Innovation Index survey saw China leading in clinical development and supply chain, while the U.S. still led in large-scale production, capital and commercialization, and talent. Respondents viewed the countries as tied in scientific discovery. Also note the psychological part. Eighty-five percent of 117 respondents said the U.S. lead will last 10 years or less.
That split tells you where the market is headed. The U.S. remains better at pricing risk, launching brands, and building global commercial machines. China is getting better at turning ideas into human assets. The bottleneck moves. For years, investors priced discovery platforms as scarce and translation as execution. Now translation itself is becoming the scarce strategic layer, and China has built a version of it that pharma can rent through licensing.
You should read this as a re-segmentation of biotech value. Discovery without fast translation loses premium. Translation without global regulatory credibility gets capped. Commercialization still wins in the U.S., but only after someone feeds it assets. The new model looks less like vertically integrated biotech and more like a global relay race where China runs the early laps and U.S. pharma runs the regulatory and commercial finish.
The field that benefits first
Oncology is the obvious winner because China has a huge patient pool, broad clinical infrastructure, and intense domestic competition. BioPharma Dive cited PitchBook’s view that China’s edge in early promising drug candidates will likely persist, and noted that from 2019 to 2023, innovative drugs submitted for human testing rose from 688 to 2,298. It also reported that since 2021, China registered nearly twice as many first-in-human trials for next-generation antibodies as the U.S. and Europe combined, including bispecifics, ADCs, and related formats.
That matters because next-generation antibodies are translation-heavy. You can talk yourself into a target forever. The real questions sit in dose, avidity, tissue distribution, linker behavior, payload tolerability, immune activation, and therapeutic index. China’s volume gives it more chances to learn those lessons in humans. The knowledge does not always show up in publications. It shows up in the second molecule, the altered linker, the cleaner dose schedule, the partner that suddenly pays $650 million upfront because it sees a platform-level learning curve.
The next wave moves beyond oncology. PitchBook expected deals to broaden into obesity, cell and gene therapy, and targeted delivery technologies. That is where the story gets more interesting. Oncology was the beachhead. The translation infrastructure now wants new payloads. Immunology, metabolic disease, and delivery are the fields to watch because they punish sloppy biology more slowly than oncology, but reward scalable trial execution and manufacturing.
The weirdest opportunity is negative selection
Here is the idea most people miss. China’s value to global pharma is not only generating winners. It also generates losers faster. That sounds cynical. It is investable.
In U.S. biotech, bad ideas often survive because capital markets need stories. A platform can keep a weak target alive through preclinical optimization, biomarkers, and “strategic optionality.” China’s throughput model creates harsher internal competition. Similar assets crowd each other. Domestic pricing pressure is brutal. If a molecule cannot separate, it struggles to command attention. That creates a form of negative selection that pharma can exploit. By the time an asset gets out-licensed with meaningful economics, it has often survived a local competitive filter.
The catch is that the filter is not the FDA. It is not a U.S. payer. It is not a Western standard-of-care environment. So you do not blindly trust it. You use it. The right diligence question becomes, “What did this asset already beat inside China’s own crowded ecosystem, and does that win matter outside China?” That is a better question than “Is China innovative?” It also gives investors a sharper way to avoid tourist trades.
What scientists should take seriously
Scientists should care because this changes how mechanisms mature. The old Western model often asks whether a target is novel enough to build a company. The China model asks whether a target can produce enough translational signal to survive asset competition. That is a different optimization function.
This means the best future translational programs will not be built around one shiny mechanism. They will be built around repeatable clinical learning loops. You want fast IND entry, flexible dose exploration, paired biomarker strategy, and a plan to read across adjacent molecules. The company that learns fastest wins even when its first drug does not. That is obvious in software. Biotech still pretends each asset is a cathedral.
For scientists, the uncomfortable lesson is that elegant biology loses to clinical iteration when the biology is only partly understood. PD-1 and VEGF bispecifics are a perfect example. You can write a beautiful mechanistic debate about co-localized blockade and tumor microenvironment remodeling. Fine. But the market moved because patients were dosed, endpoints were hit, and competitors had to react. Translation forced the theory to become real.
What investors should stop underwritingWatch human genetics.
Stop paying full platform multiples for U.S. companies that cannot explain why their first-in-human path is faster, cleaner, or more globally defensible than a Chinese competitor. “We have proprietary discovery” is not enough. Proprietary discovery has become table stakes. The question is whether the company has a translation edge that survives global competition.
The vulnerable U.S. profiles are easy to spot.
A preclinical multispecific platform with no human data and no clear safety logic
An ADC company with familiar payloads, crowded targets, and expensive Western trials
An immunology story that leans on target novelty but lacks clinical biomarkers
A rare disease company that assumes FDA flexibility offsets weak execution
A company that says “China risk” but cannot name the Chinese assets in its own lane
The winners look different. They use China strategically without becoming dependent on China. They know which patient populations translate and which do not. They design global bridging early. They treat manufacturing as part of the asset, not a vendor line item. They also know when to partner before the U.S. trial bill eats the whole balance sheet.
The geopolitical bear case is real
This trade has a policy ceiling. BioPharma Dive reported that a new House bill would subject licensing deals, joint ventures, and equity investments involving China to Treasury and Defense Department reviews. The same report cited lawmakers saying cross-border licensing transactions reached $136 billion last year, up from less than $5 billion in 2020. That is exactly the kind of number Washington notices.
The risk is not that U.S. pharma stops licensing Chinese assets tomorrow. That is too blunt. The risk is friction. Reviews slow deals. Sensitive technologies get carved out. Data transfer becomes harder. Manufacturing plans shift to North America or Europe. Deal structures become more complex. Upfronts become tied to regulatory certainty. The market can still function, but the easy arbitrage narrows.
This is where investors need to stay cold. Geopolitical risk cuts both ways. It can hurt Chinese licensors and U.S. licensees. It can also increase the value of U.S. companies with credible comparable assets if China access gets constrained. The right trade is not “buy China” or “short U.S.” The right trade is to map which therapeutic classes depend on Chinese translational volume and which companies have a fallback if that channel gets taxed.
The U.S. response confirms the threat
The FDA’s Operation TrialBlazer is the tell. Reuters reported that FDA announced measures on June 22, 2026 to speed drug research from early investigational studies to late-stage trials. The goal is obvious. The U.S. wants to bring early clinical work back home because the trial layer has strategic value.
IQVIA’s 2026 R&D report also flagged that development timelines have increased, inter-trial intervals rose by three months, and sponsors plus regulators are pursuing acceleration activities. It noted that China-headquartered and international company deals reached an all-time high. Put those together and you get a clear picture. The U.S. is trying to fix cycle time while China is monetizing it.
This matters because the U.S. does not need to copy China exactly. It needs to reduce the penalty for doing fast, high-quality early trials domestically. If TrialBlazer works, U.S. biotech gets some oxygen. If it turns into another acronym with uneven implementation, China’s relative advantage persists. Watch the actual IND-to-first-patient timelines, not the press releases.
The hidden pricing problem
China also changes drug pricing in a way investors do not like to discuss. A Chinese-origin asset with lower development cost and a motivated global partner can pressure the pricing umbrella for crowded classes. The first obvious place is oncology combinations. The second is obesity if China-generated incretin or amylin assets enter global development at scale. The third is autoimmune disease, where payers already hate chronic biologic costs.
This does not mean Chinese assets launch cheap in the U.S. U.S. partners will price like U.S. partners. But lower acquisition cost changes portfolio math. A pharma company that buys a credible asset for $80 million upfront or even $650 million upfront has more strategic room than a company that spent $3 billion internally before Phase 3. It can tolerate narrower markets. It can run more combinations. It can abandon faster.
That hurts U.S. small caps relying on scarcity. If a target class has five Chinese entrants with human data, your U.S. asset needs more than “best-in-class potential.” It needs proof. The phrase “best-in-class potential” should now be treated as a warning label unless management can show why the molecule wins on dose, schedule, safety, manufacturing, and trial design.
What this means for future therapeutic development
The future model is a split-stack system. China will generate more early human packages across crowded, high-value biology. Western pharma will license, globalize, and commercialize the survivors. U.S. biotech will still matter, especially in frontier biology, rare disease, modality invention, and commercial strategy. But the middle layer gets squeezed. That middle layer is where many venture-backed platforms live.
Translation development will become more comparative. You will not ask whether a molecule works in isolation. You will ask whether it works better than the fastest global analog. That means diligence must include Chinese-language trial registries, NMPA filings, local competitor scans, and manufacturing reality checks. Investors who ignore that work will keep getting surprised by “sudden” deals that were visible two years earlier.
The best opportunity sits in companies that can bridge worlds. Not generic China exposure. Not blind BD roll-ups. The winners will understand how to take Chinese-origin data, identify what is real, fix what is not FDA-ready, and design global trials that answer the questions Western regulators and payers actually ask. That is a skill set. It deserves a premium.
The bear case nobody should skip
The FDA’s Operation TrialBlazer is the tell. Reuters reported that FDA announced measures on June 22, 2026 to speed drug research from early investigational studies to late-stage trials. The goal is obvious. The U.S. wants to bring early clinical work back home because the trial layer has strategic value.
IQVIA’s 2026 R&D report also flagged that development timelines have increased, inter-trial intervals rose by three months, and sponsors plus regulators are pursuing acceleration activities. It noted that China-headquartered and international company deals reached an all-time high. Put those together and you get a clear picture. The U.S. is trying to fix cycle time while China is monetizing it.
This matters because the U.S. does not need to copy China exactly. It needs to reduce the penalty for doing fast, high-quality early trials domestically. If TrialBlazer works, U.S. biotech gets some oxygen. If it turns into another acronym with uneven implementation, China’s relative advantage persists. Watch the actual IND-to-first-patient timelines, not the press releases.
The specific ideas worth watching
Here are the areas where I would spend time before the market makes them obvious.
PD-1 and VEGF follow-ons where the molecule is not the story, but the global trial design is
ADCs with China-origin linker or payload learning that Western companies quietly license before Phase 2
Obesity assets where China supplies speed and patient volume, then U.S. partners supply commercial scale
Autoimmune bispecifics where China’s oncology antibody engineering gets repurposed into chronic disease
Cell therapy manufacturing platforms that look boring until they lower COGS enough to change access
Delivery technologies that make RNA, gene editing, or tissue-targeted biologics less dependent on Western platform premiums
The interesting trade is not to buy the loudest China biotech ADR. The better trade is to find U.S. and European companies whose valuation still assumes local scarcity in a global asset market. Some are overvalued. Some become acquisition targets because pharma needs a non-China backup. Some deserve lower multiples because their “novel” program already has Chinese human data competitors.
That is the part investors will miss because it requires work. You need to know the China assets before they become English-language press releases. You need to know which mechanisms travel. You need to know which data packages will make FDA reviewers uncomfortable. Most people will wait for Pfizer, BMS, Merck, or AbbVie to tell them what mattered. By then, the easy money is gone.
Final setup
China did not just become a biotech competitor. It built a translation layer that changes how therapeutic ideas become assets. That layer sits between discovery and global commercialization. It is fast. It is uneven. It is politically exposed. It is already important.
The opportunity is not simple. You do not get to say China wins and stop thinking. You also do not get to dismiss it as cheap me-too biotech. The right answer is more annoying. China has created a high-volume clinical learning system that produces enough real assets to pressure U.S. platform valuations, feed Big Pharma pipelines, and force regulators to care about early trial speed again.
CONCLUSION
Today, the takeaway is simple. China did not just add more biotech supply. It changed the cost and speed of turning biology into a licensable therapeutic asset. That hurts lazy U.S. platform stories. It helps pharma buyers with global BD reach. It also creates real diligence work for everyone else. You need to know which Chinese assets are already in your target class, which data packages translate, and which mechanisms only look good inside a local trial ecosystem. Some of these drugs will fail outside China. Many should. But enough will work to reset how the industry prices scarcity. The next biotech winner will not be the company with the cleanest discovery slide. It will be the one that learns in humans faster, knows when to partner, and understands that translation has become the battlefield.
We are now publishing 7x per week according to the following cadence:
Mondays: Stocks
Tuesdays: Biotech
Wednesdays: Podcast
Thursdays: Markets
Fridays: News
Saturdays: Podcast
Sundays: Strategy
SUBSCRIBE TO PODCAST HERE:
Sundays and Mondays are under the paid umbrella, everything else is FREE. It is $11.99/month and we encourage you to support our efforts. It keeps us motivated to keep producing the hybrid science and business biotech focused content you will not find anywhere else all in the same place.
As a reminder, if looking to go deeper into the topics we cover check out our website BowTiedBiotech.com, or DM us on twitter, or email us: bowtiedbiotech@gmail.com
ABOUT BOWTIEDBIOTECH
As a reminder, the purpose of the BowTiedBiotech substack is two-fold. Primarily, we aim to provide our scientist audience the tools to build a biotech company and ultimately translate their ideas into medicines for patients. Secondarily, biotech investors may find this substack useful as we will be providing weekly market updates of the public AND private markets as well as heavily leveraging current financing events as teaching examples.
DISCLAIMER
None of this is to be deemed legal or financial advice of any kind. All updates are sourced from publicly available disclosures. Insights are *opinions* written by an anonymous cartoon/scientist/investor.