
Hello Avatar! Welcome to another week of biotech analysis. Today’s commentary, as always on Thursday, focuses on the general market update. This week confirmed the playbook. Biotech can rally and capital can return quickly, but funding is flowing to companies with clean catalysts and tight execution. Secondaries continue to dominate the financing landscape, while IPO activity remains scarce. Investors are rewarding near-term proof and punishing duration risk. In this environment, cost of capital shapes trial design, and clock discipline matters as much as mechanism.
We are now publishing 7x per week according to the following cadence:
Mondays: Stocks
Tuesdays: Biotech
Wednesdays: Podcast
Thursdays: Markets
Fridays: News
Saturdays: Podcast
Sundays: Strategy
We are also publishing unique content on X - be sure to follow up if you are not already @BowTiedBiotech. And to check-out the archive of our work on X you can find it on our website at: BowtiedBiotech.subtack.com/x-articles.
SUBSCRIBE TO PODCAST HERE:
Please help spread the work by subscribing and hitting the share button if you are enjoying content!
Lots to cover this week, let's get started!
BIOTECH PUBLIC MARKET UPDATE
For the week, the public indexes were UP, with the S&P +0.9% and DOW moving +0.7%. For the year the public indexes are UP, with the S&P up +9.6% and DOW up +7.3%. The XBI (the biotech index) comes in UP approximately +1.5% for the week and is up approximately +11.0% for the year.

Macro Update
Most investors view inflation as a macro problem. The Fed worries about it. Bond markets react to it. Consumers feel it at the grocery store. Biotech appears several steps removed from the discussion.
Look closer. Biotechnology is one of the most interest-rate sensitive sectors in the market. Most companies generate little or no revenue. Their value comes from cash flows that may not arrive for five, ten, or even fifteen years. When inflation remains elevated, interest rates stay higher for longer. When rates stay elevated, future cash flows become less valuable. The result is lower valuations, tighter financing conditions, and less investor appetite for risk.
The latest inflation data suggest the market may not be getting the rapid easing cycle it expected at the beginning of the year. That matters because much of the biotech recovery thesis depended on lower rates reopening capital markets. Instead, investors are being forced to confront a more challenging environment. Cash remains expensive. Dilution remains a risk. Companies without near-term catalysts face increasing pressure to justify their valuations.
This dynamic does not impact every biotech equally. Late-stage companies with strong balance sheets, partnered assets, and clear paths to commercialization can still attract capital. Early-stage platform stories and preclinical companies face a much higher bar. Investors are becoming more selective. They want human data. They want validated biology. They want proof that a company can survive long enough to reach meaningful inflection points.
The market still treats inflation as a broad economic story. That is likely a mistake. For biotech, inflation ultimately becomes a financing story. The companies that survive this environment will not necessarily have the most exciting science. They will be the ones with enough cash, enough validation, and enough time to let the science matter.
Introduction
This week we're stepping back from individual companies to examine a question hiding in plain sight. Why has biotechnology produced more scientific breakthroughs, higher clinical success rates, and more approved medicines while investor returns have remained so disappointing? The answer may reveal a major shift occurring across the industry. Biology is becoming abundant. Certainty is becoming scarce. And the companies that profit over the next decade may look very different from those that won in the last one.
Why biotech investors keep losing despite scientific progress
Every few years the biotech industry tells itself the same story.
We understand biology better. We have better tools. We sequence genomes faster. We design molecules more intelligently. We fail less often.
The data support that view. Clinical success rates have improved. More mechanisms reach approval. More diseases have effective treatments. By almost any scientific measure, biotechnology continues advancing.
Yet biotech investors face a different reality.
Scientific progress and shareholder returns have separated.
Most investors assume better science should produce better businesses. The success-rate data suggest a different possibility. The industry may be getting better at creating medicines while simultaneously becoming worse at creating scarcity.
The industry celebrates higher success rates. Investors should ask a different question.
Who captures the value created by those higher success rates?
Those are not always the same companies.
The industry may be solving its own profitability problem
The bull case is obvious. If more drugs work, more companies should win.
The bear case is more interesting.
Every improvement in biological understanding makes biological understanding less scarce. Sequencing costs collapsed. Human genetics scaled. Single-cell biology exploded. AI accelerated target generation. The industry became dramatically better at producing insight.
It also became easier.
Twenty years ago identifying a promising pathway created a meaningful moat. Today multiple companies often reach similar conclusions at roughly the same time. The science improved. The competitive advantage shrank.
The first company captures uncertainty. The tenth company captures competition.
That distinction explains far more biotech returns than most investors appreciate.
The obesity lesson everybody got wrong
Most investors view obesity as proof that breakthrough biology creates enormous returns.
They are right. But they often misunderstand where those returns came from.
The largest gains were earned before everyone agreed the biology worked. During that period uncertainty remained high, capital remained limited, and competition remained manageable.
Once the biology became obvious, money flooded into the space. New entrants emerged. Alternative mechanisms appeared. Combination therapies followed. The opportunity became larger, but it also became more crowded.
Patients benefit from that process.
Investors face a different outcome.
Scientific certainty increases. Scarcity declines.
The same pattern appears repeatedly throughout biotechnology.
The bottleneck has moved
Most investors still believe target discovery is the industry’s most valuable activity.
That assumption made sense twenty years ago.
Today the industry generates targets faster than it can validate them. Human genetics identifies associations at scale. AI generates hypotheses. Academic labs publish thousands of new observations every year.
The problem is no longer finding ideas.
The problem is determining which ideas actually matter in humans.
Discovery creates possibilities.
Validation removes uncertainty.
Increasingly, pharmaceutical companies pay for the second.
Watch where acquisition dollars flow. Most billion-dollar deals occur after proof-of-concept. Pharma is not buying interesting biology. Pharma is buying evidence.
Why translation is becoming the product
This is where the story gets interesting.
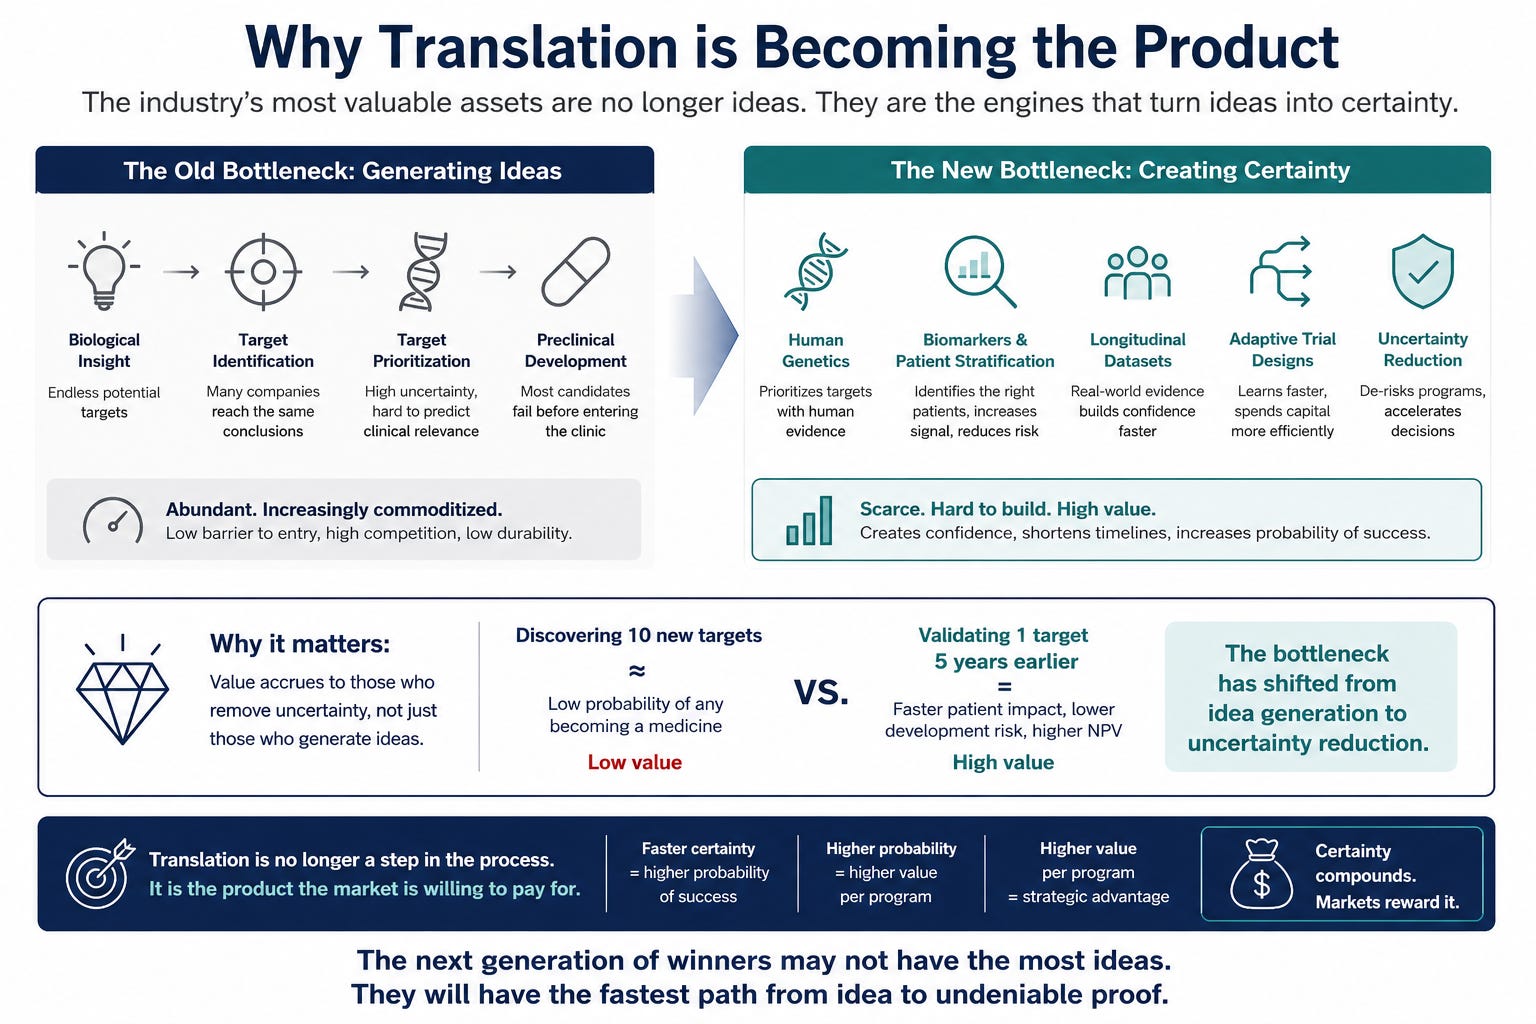
Most investors think of translation as a process. The industry increasingly treats it as an asset.
Human genetics. Biomarkers. Patient stratification. Longitudinal datasets. Adaptive trial designs.
These are often viewed as supporting tools. They may ultimately become more valuable than many therapeutic platforms.
Why?
Because they accelerate certainty.
A company that validates a target five years earlier creates more value than a company that discovers ten additional targets nobody can prove.
The bottleneck is shifting from idea generation to uncertainty reduction.
The market has not fully adjusted to that reality.
The AI story nobody wants to hear
Most discussions around AI focus on designing better drugs.
That may happen.
The larger economic opportunity is killing bad programs earlier.
Every failed Phase 2 trial destroys time, capital, and opportunity cost. A system that identifies likely failures before they reach expensive clinical studies creates enormous value.
That outcome is less exciting than generating novel molecules.
It is also far more important.
The companies creating the most value may not generate more shots on goal. They may simply eliminate bad shots before they are taken.
Pharma is already telling you the answer
Investors spend a lot of time debating where biotechnology is heading.
Pharma has already voted.
Large pharmaceutical companies increasingly acquire assets after clinical validation rather than before. They allow smaller companies to absorb early uncertainty and then pay substantial premiums once the biology works.
That behavior reveals where value sits.
Not in generating hypotheses.
In removing risk.
Every licensing agreement tells the same story. The largest checks follow human validation.
Confidence commands a premium.
What nobody is saying out loud
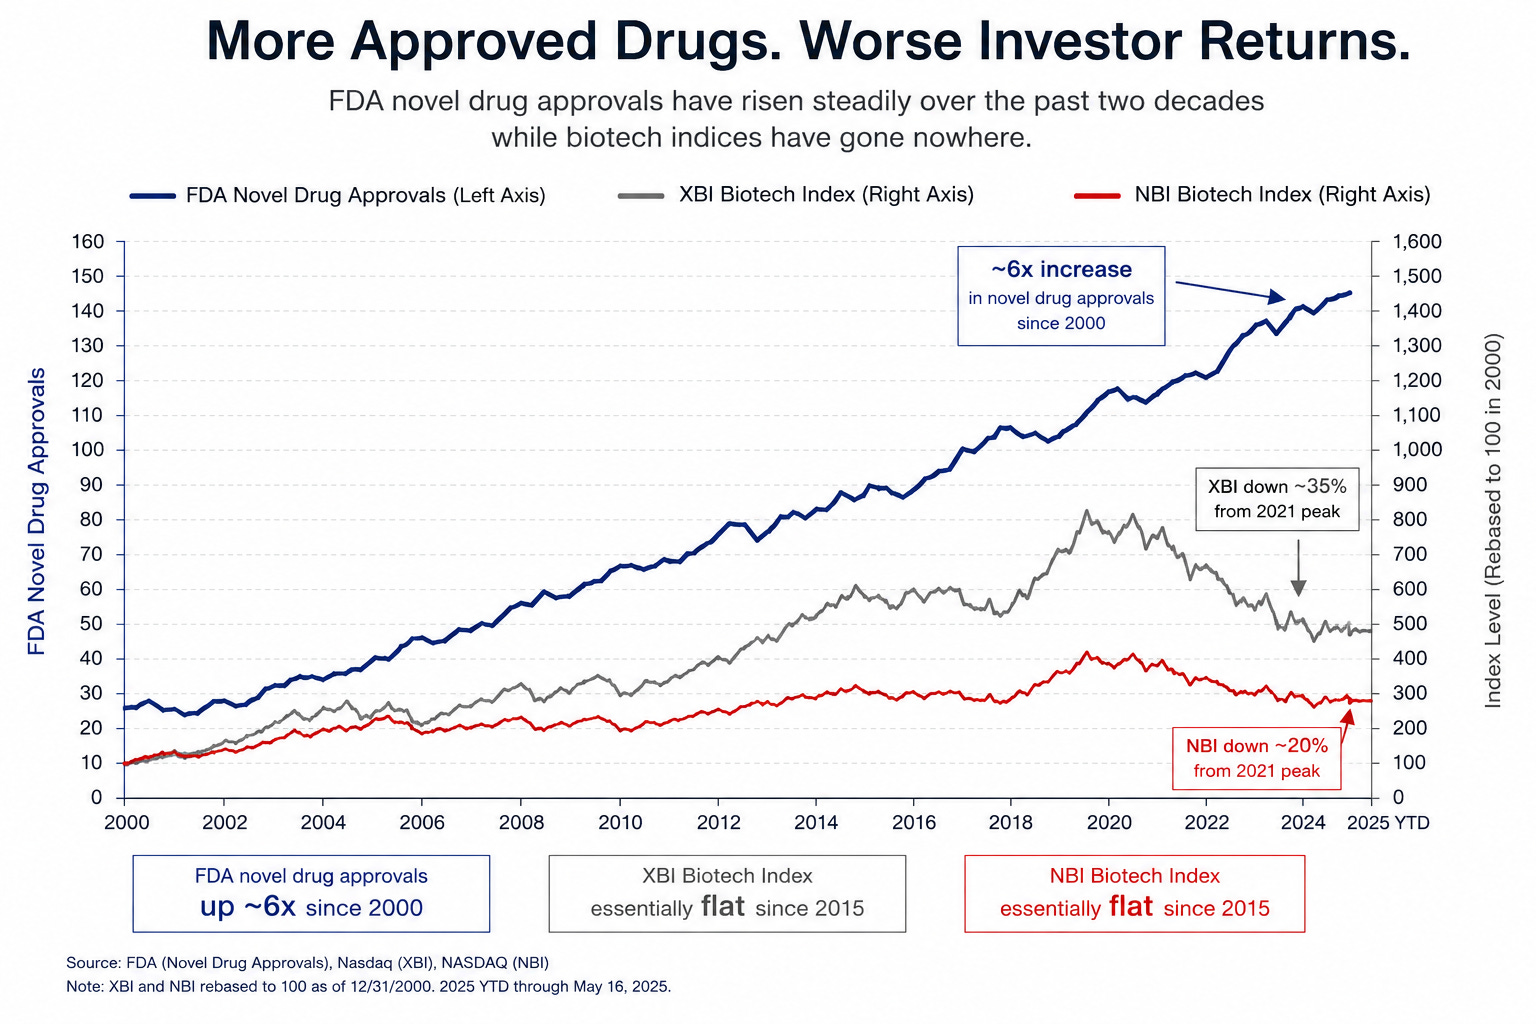
The industry may be entering a period where drug approvals continue rising while investment returns continue falling.
Most investors assume those variables move together.
They don’t have to.
As biology becomes easier to understand, more organizations can participate. As more organizations participate, competition increases. As competition increases, scarcity declines.
Society benefits enormously.
Shareholders do not necessarily capture the gains.
That may be the defining investment challenge of the next decade.
The short thesis
Biology is becoming abundant.
Translation is becoming scarce.
Investors still value biotechnology as though discovery remains the primary bottleneck. Increasingly the valuable asset is certainty.
The winners of the next decade may not be the companies with the most targets.
They may be the companies that remove uncertainty faster than everyone else.
What to watch next
Watch human genetics.
Watch biomarker adoption.
Watch adaptive clinical trial designs.
Watch who owns the best patient datasets.
Watch where pharma writes acquisition checks.
Most importantly, watch who can kill programs early.
That is where value increasingly accumulates.
Final read
The success-rate data tell a more interesting story than most readers realize.
Drug development is improving. Biology is becoming easier to understand. More therapies will reach patients over the next decade than most people expect.
At the same time, scientific progress is reducing the scarcity that once generated extraordinary returns.
The market continues searching for better biology.
The bigger opportunity may be identifying who profits when better biology becomes common.
Those are not always the same companies.
And that is where the next generation of biotech winners will emerge.
CONCLUSION
Today, the biotechnology industry is producing more validated biology, more approved drugs, and more scientific breakthroughs than at any point in its history. Yet the greatest investment opportunities may no longer come from discovering new targets. They may come from reducing uncertainty faster than everyone else. As biology becomes increasingly abundant, value is shifting toward translation, validation, and the systems that turn promising ideas into undeniable proof. The market still rewards innovation. Increasingly, it pays a premium for certainty.
We are now publishing 7x per week according to the following cadence:
Mondays: Stocks
Tuesdays: Biotech
Wednesdays: Podcast
Thursdays: Markets
Fridays: News
Saturdays: Podcast
Sundays: Strategy
SUBSCRIBE TO PODCAST HERE:
Sundays and Mondays are under the paid umbrella, everything else is FREE. It is $11.99/month and we encourage you to support our efforts. It keeps us motivated to keep producing the hybrid science and business biotech focused content you will not find anywhere else all in the same place.
As a reminder, if looking to go deeper into the topics we cover check out our website BowTiedBiotech.com, or DM us on twitter, or email us: bowtiedbiotech@gmail.com
ABOUT BOWTIEDBIOTECH
As a reminder, the purpose of the BowTiedBiotech substack is two-fold. Primarily, we aim to provide our scientist audience the tools to build a biotech company and ultimately translate their ideas into medicines for patients. Secondarily, biotech investors may find this substack useful as we will be providing weekly market updates of the public AND private markets as well as heavily leveraging current financing events as teaching examples.
DISCLAIMER
None of this is to be deemed legal or financial advice of any kind. All updates are sourced from publicly available disclosures. Insights are *opinions* written by an anonymous cartoon/scientist/investor.